Why the IRS Treats Your RESP Like a Foreign Trust, Not a College Savings Plan
A parent in Vancouver opens an RESP for her daughter, receives the federal grant of 20% on the first $2,500 contributed, and watches the account grow tax-free. Five years later, when she files her U.S. tax return, she discovers she owes taxes on every dollar of growth since the day she opened the account, plus penalties for failing to file forms she'd never heard of. Canada designed the RESP as a tax-incentive vehicle to encourage education savings. The IRS sees a grantor trust held offshore, subject to the same reporting regime as a Swiss private trust or a Caribbean shell entity.
Why the RESP Falls Outside Treaty Protection
The 2007 protocol to the Canada-U.S. Tax Treaty clarified tax-deferred treatment for RRSPs and RRIFs. RESPs were deliberately excluded. Unlike retirement accounts, which benefit from explicit treaty recognition, education savings plans produce no parallel benefit under U.S. tax law. The IRS does not recognize registered status as meaningful. What matters is structure: who controls the account, who receives the income, and whether the vehicle qualifies as a foreign trust under Sections 671 through 679 of the Internal Revenue Code.
When a U.S. citizen acts as the RESP subscriber, the account is treated as a grantor trust. Under grantor trust rules, all income earned inside the trust, interest, dividends, capital gains, is attributed annually to the subscriber and taxed in the year earned, whether or not any money is withdrawn. The tax-free growth that makes RESPs attractive to Canadian families disappears entirely for dual citizens.
The Grant Creates Immediate Taxable Income
The Canada Education Savings Grant is taxable in Canada only when withdrawn by the student. The IRS treats it as taxable income to the subscriber in the year it is deposited. A $500 annual grant is $500 of ordinary income for U.S. tax purposes, taxed at the subscriber's marginal rate. Provincial grants follow the same treatment. What Canada frames as a benefit becomes a tax event with no offsetting deduction.
Reporting Requirements Compound the Burden
Form 3520 and Form 3520-A are mandatory filings for U.S. persons with ownership or control of a foreign trust. These forms track contributions, distributions, and accumulated income. Failure to file triggers penalties starting at $10,000 USD or 35% of the gross value of property transferred to the trust, whichever is greater. The filing requirement applies even if the RESP has a balance under $10,000.
The account must also be reported on the FBAR if the subscriber's combined foreign account balances exceed $10,000 USD at any point during the year. Canadian mutual funds or ETFs held inside the RESP may trigger Passive Foreign Investment Company reporting on Form 8621, adding another layer of complexity and punitive tax treatment.
The Professional Cost Exceeds the Grant
Specialized cross-border tax preparation for a foreign trust typically costs between $1,500 and $3,000 USD per year. For middle-income families, the cost of staying compliant quickly exceeds the value of the federal grant. Revenue Procedure 2020-17 offers simplified reporting for certain foreign retirement and savings accounts, but it does not exempt the income from annual taxation, only the forms.
The Workaround Involves Giving Up Control
The most common planning strategy is transferring the subscriber role to a non-U.S. person, typically a Canadian grandparent. As long as the subscriber is not a U.S. citizen or resident, the trust remains outside U.S. tax jurisdiction until the student receives Educational Assistance Payments. At that point, if the student is also a dual citizen, the distributions become taxable. During the accumulation years before withdrawal, the income accrues free of U.S. annual tax.
Canada built a system to make education savings easier. The U.S. tax code treats that system as offshore wealth planning, and taxes it accordingly.
Internal Revenue Service - Failure to file triggers penalties starting at $10,000 USD or 35% of the gross value of property transferred to the trus - 2025-12. https://www.irs.gov/instructions/i3520
Internal Revenue Service - Revenue Procedure 2020-17 offers simplified reporting for certain foreign retirement and savings accounts - 2020-03. https://www.irs.gov/pub/irs-drop/rp-20-17.pdf


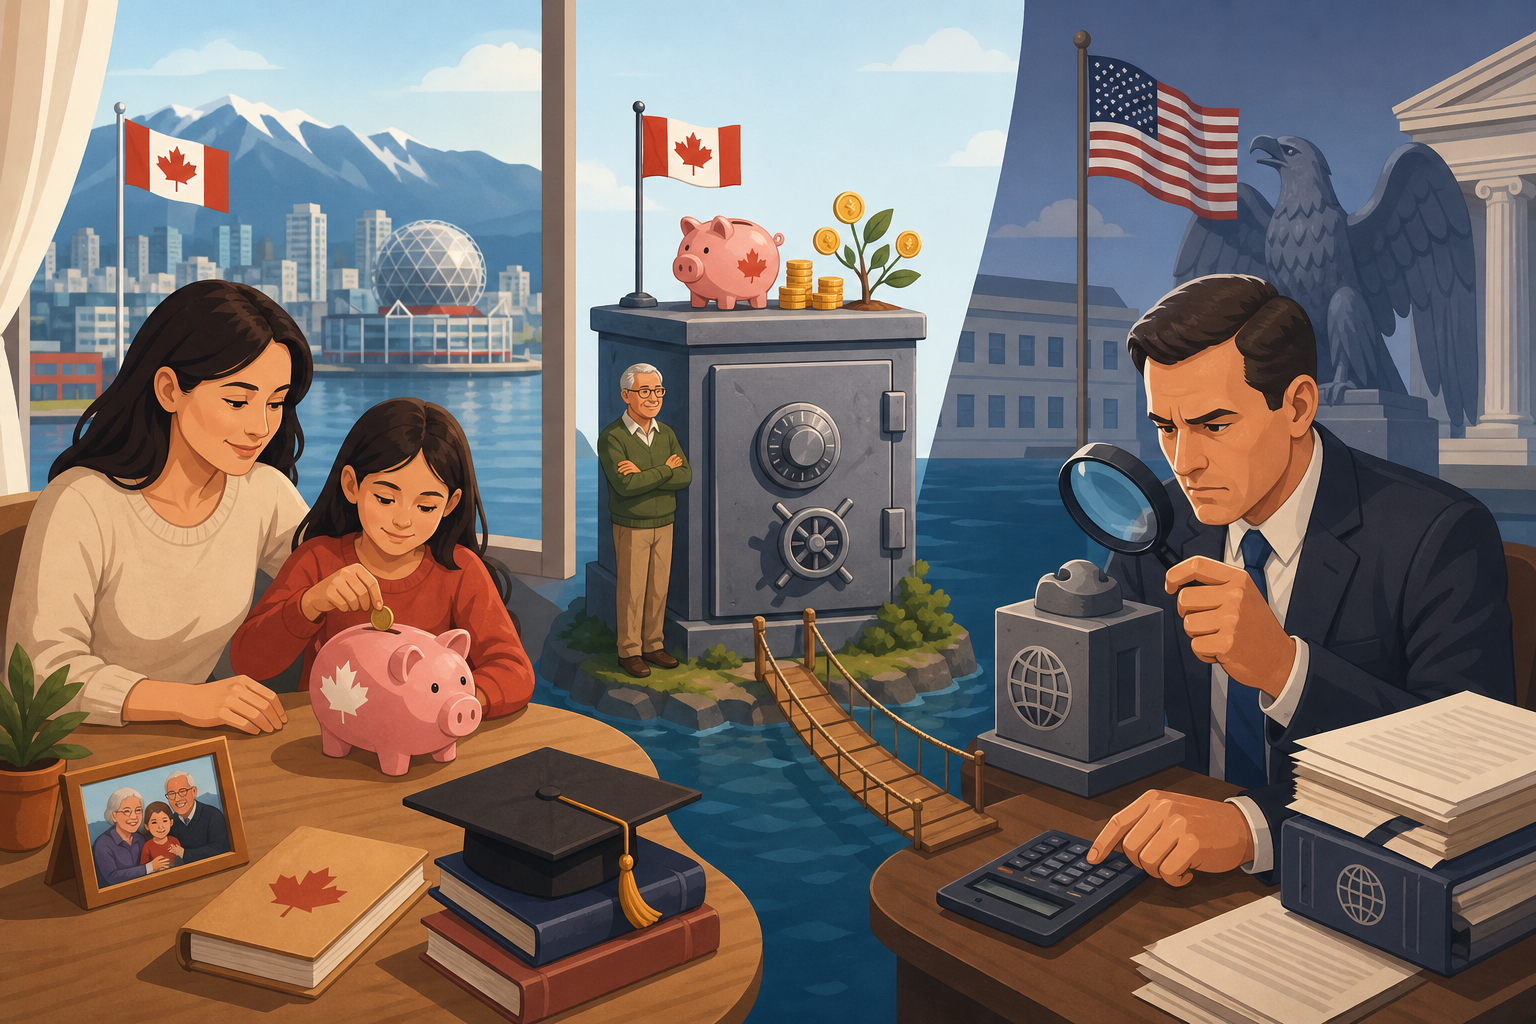

A parent in Vancouver opens an RESP for her daughter, receives the federal grant of 20% on the first $2,500 contributed, and watches the account grow tax-free. Five years later, when she files her U.S. tax return, she discovers she owes taxes on every dollar of growth since the day she opened the account, plus penalties for failing to file forms she'd never heard of. Canada designed the RESP as a tax-incentive vehicle to encourage education savings. The IRS sees a grantor trust held offshore, subject to the same reporting regime as a Swiss private trust or a Caribbean shell entity.
Why the RESP Falls Outside Treaty Protection
The 2007 protocol to the Canada-U.S. Tax Treaty clarified tax-deferred treatment for RRSPs and RRIFs. RESPs were deliberately excluded. Unlike retirement accounts, which benefit from explicit treaty recognition, education savings plans produce no parallel benefit under U.S. tax law. The IRS does not recognize registered status as meaningful. What matters is structure: who controls the account, who receives the income, and whether the vehicle qualifies as a foreign trust under Sections 671 through 679 of the Internal Revenue Code.
When a U.S. citizen acts as the RESP subscriber, the account is treated as a grantor trust. Under grantor trust rules, all income earned inside the trust, interest, dividends, capital gains, is attributed annually to the subscriber and taxed in the year earned, whether or not any money is withdrawn. The tax-free growth that makes RESPs attractive to Canadian families disappears entirely for dual citizens.
The Grant Creates Immediate Taxable Income
The Canada Education Savings Grant is taxable in Canada only when withdrawn by the student. The IRS treats it as taxable income to the subscriber in the year it is deposited. A $500 annual grant is $500 of ordinary income for U.S. tax purposes, taxed at the subscriber's marginal rate. Provincial grants follow the same treatment. What Canada frames as a benefit becomes a tax event with no offsetting deduction.
Reporting Requirements Compound the Burden
Form 3520 and Form 3520-A are mandatory filings for U.S. persons with ownership or control of a foreign trust. These forms track contributions, distributions, and accumulated income. Failure to file triggers penalties starting at $10,000 USD or 35% of the gross value of property transferred to the trust, whichever is greater. The filing requirement applies even if the RESP has a balance under $10,000.
The account must also be reported on the FBAR if the subscriber's combined foreign account balances exceed $10,000 USD at any point during the year. Canadian mutual funds or ETFs held inside the RESP may trigger Passive Foreign Investment Company reporting on Form 8621, adding another layer of complexity and punitive tax treatment.
The Professional Cost Exceeds the Grant
Specialized cross-border tax preparation for a foreign trust typically costs between $1,500 and $3,000 USD per year. For middle-income families, the cost of staying compliant quickly exceeds the value of the federal grant. Revenue Procedure 2020-17 offers simplified reporting for certain foreign retirement and savings accounts, but it does not exempt the income from annual taxation, only the forms.
The Workaround Involves Giving Up Control
The most common planning strategy is transferring the subscriber role to a non-U.S. person, typically a Canadian grandparent. As long as the subscriber is not a U.S. citizen or resident, the trust remains outside U.S. tax jurisdiction until the student receives Educational Assistance Payments. At that point, if the student is also a dual citizen, the distributions become taxable. During the accumulation years before withdrawal, the income accrues free of U.S. annual tax.
Canada built a system to make education savings easier. The U.S. tax code treats that system as offshore wealth planning, and taxes it accordingly.
Sources
Read Next
7 Essential Checks Before You Buy in 2026: Building Confidence Through the Numbers
Getting Lenders to Count 80% of Your Gross Rent: A Checklist
820 Low-Rise Homes, 129 Condos: The GTA Slump Belongs to Speculators
200 Basis Points or 2 Percentage Points: Same Stress Test, Clearer Wording