The Bank of Canada Won't Move Rates in 2026 Because Nothing Forces Its Hand
Tiff Macklem faces three choices every six weeks. Cut, raise, or do nothing. He has picked nothing eight times in a row, and October will mark the full 12-month anniversary of the last move, which reset the rate to 2.25%.
Nobody is forcing him to change that. Inflation keeps retreating just as it threatens. GDP dodges technical recession just in time. Employment figures show no shock that would demand action. Macklem is a central banker, and the path of least resistance is precisely where he wants to be.
The One-Job Problem
Macklem technically oversees the mint, signs off on commemorative coins, picks which faces go on the currency. None of that matters. He has one job that dwarfs everything else: deciding the overnight rate eight times a year. Get that wrong and nobody will remember the other stuff fondly.
The current rate sits at 2.25%, the lower bound of what the Bank calls its neutral range, which runs to 2.75%. Neutral means the rate neither stimulates nor restricts growth. It is the Goldilocks band where the governor can sit without defending the choice every quarter. The problem is that neutral also means there is no urgency to move, and urgency is what drives a rate change. Without it, the default is always hold.
No Catastrophe, No Movement
A rate cut requires tanking GDP or spiking unemployment. A hike requires runaway inflation or an overheating economy. Canada has delivered neither. Inflation flickers and fades. Growth wobbles but avoids collapse. The labor market softens without breaking. Every data release has been just weak enough to worry about, but not weak enough to act on. Trump's tariff threats have been live since early 2025, and every Canadian central banker knows cross-border trade drives the economy in ways domestic policy cannot fix. Macklem cannot cut his way out of a tariff shock, and he cannot hike into a slowdown caused by falling exports.
Being right about a change earns you no compliments for 18 months, because monetary policy works on a lag and nobody knows if you were correct until the effects show up. Macklem thinks about employment, GDP, housing, and the shadow of his predecessor, Mark Carney, whose influence still shapes how Canadian central bankers see their role. Ignoring all that and cutting rates because inflation dipped to 1.8% for one quarter would be a political gamble Macklem will not take.
The Safest Call Is No Call
Making a change attracts attention. Being wrong about a change guarantees you hear about it for years. Being right about a change earns you no compliments for 18 months, because monetary policy works on a lag and nobody knows if you were correct until the effects show up. The asymmetry is brutal: all the risk, none of the reward, until long after you have left the job.
Doing nothing when the data is ambiguous is the rational play. It keeps you out of the headlines. It avoids the need to explain why you moved when everyone else was holding. It gives you the option to move later if the data actually turns. Macklem has learned this lesson, and he is applying it.
Variable-rate holders benefit from the stability for now. The longer the rate holds at 2.25%, the safer their position feels. But stability is not safety. When inflation does spike, and the commodity cycle, food prices, and global bond yields all suggest it will, fixed rates will have already climbed, and the window to lock in will have closed. By the time Macklem moves, it will be too late to escape cheaply.
The last two meetings of 2026 are in October and December. Barring catastrophic data, unemployment jumping to 12%, inflation spiking to 6%, GDP collapsing by 3% in a quarter, neither will produce a change. The governor has no compelling reason to act, and in central banking, no compelling reason means no action. That is the reality for the rest of the year.


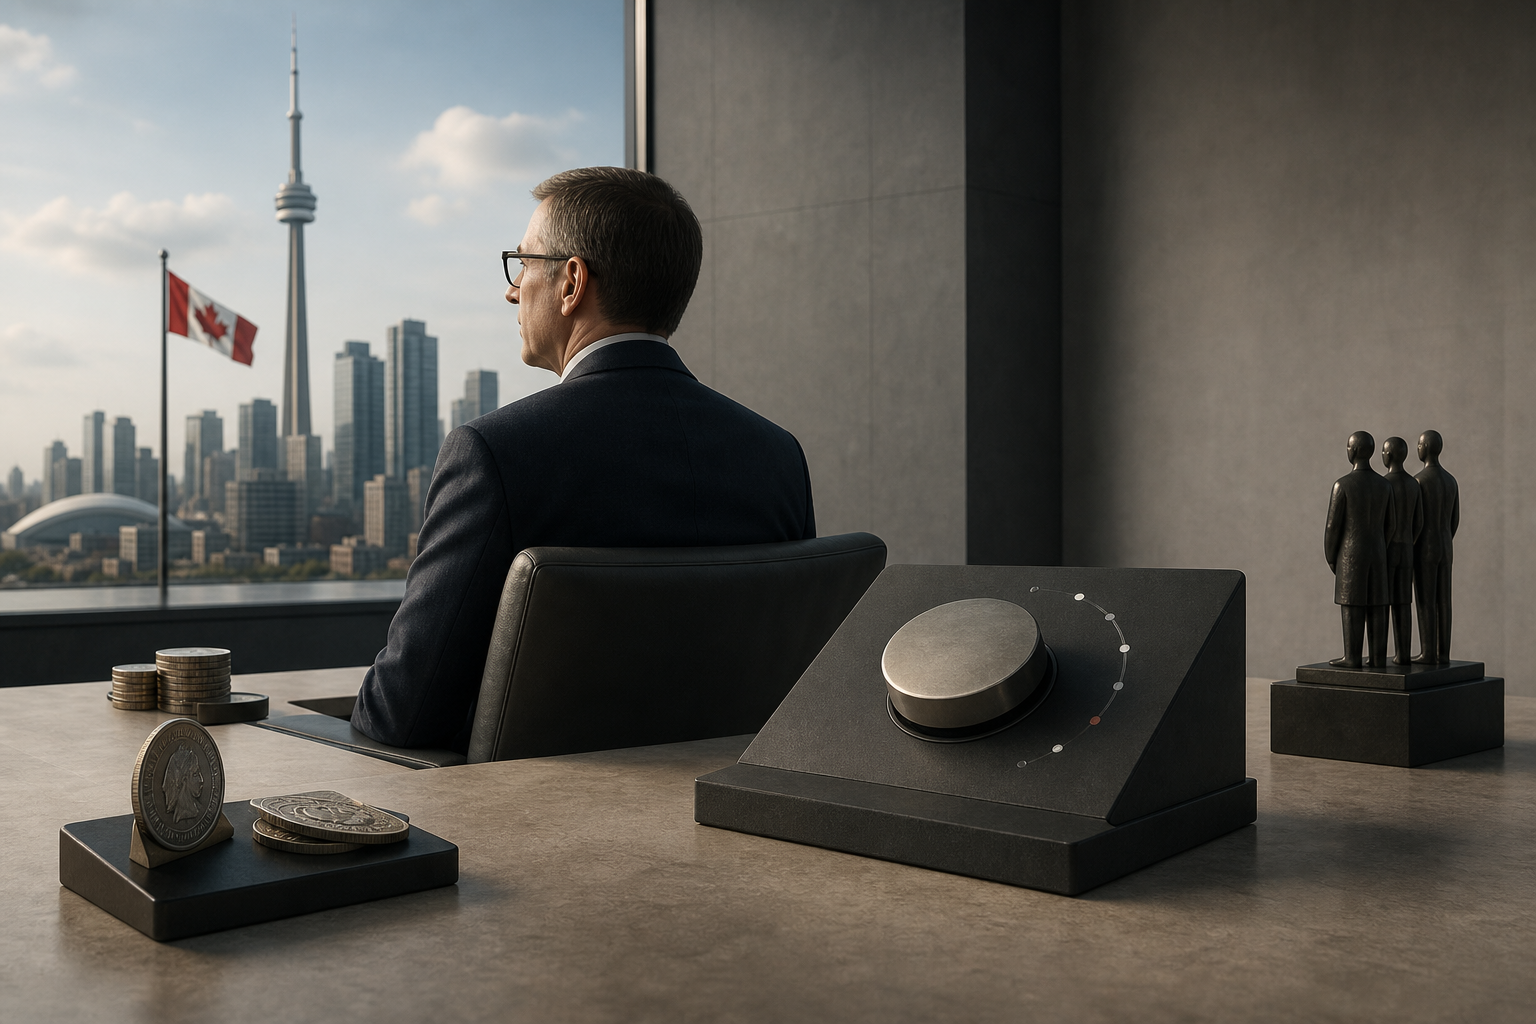

Tiff Macklem faces three choices every six weeks. Cut, raise, or do nothing. He has picked nothing eight times in a row, and October will mark the full 12-month anniversary of the last move, which reset the rate to 2.25%.
Nobody is forcing him to change that. Inflation keeps retreating just as it threatens. GDP dodges technical recession just in time. Employment figures show no shock that would demand action. Macklem is a central banker, and the path of least resistance is precisely where he wants to be.
The One-Job Problem
Macklem technically oversees the mint, signs off on commemorative coins, picks which faces go on the currency. None of that matters. He has one job that dwarfs everything else: deciding the overnight rate eight times a year. Get that wrong and nobody will remember the other stuff fondly.
The current rate sits at 2.25%, the lower bound of what the Bank calls its neutral range, which runs to 2.75%. Neutral means the rate neither stimulates nor restricts growth. It is the Goldilocks band where the governor can sit without defending the choice every quarter. The problem is that neutral also means there is no urgency to move, and urgency is what drives a rate change. Without it, the default is always hold.
No Catastrophe, No Movement
A rate cut requires tanking GDP or spiking unemployment. A hike requires runaway inflation or an overheating economy. Canada has delivered neither. Inflation flickers and fades. Growth wobbles but avoids collapse. The labor market softens without breaking. Every data release has been just weak enough to worry about, but not weak enough to act on. Trump's tariff threats have been live since early 2025, and every Canadian central banker knows cross-border trade drives the economy in ways domestic policy cannot fix. Macklem cannot cut his way out of a tariff shock, and he cannot hike into a slowdown caused by falling exports.
Being right about a change earns you no compliments for 18 months, because monetary policy works on a lag and nobody knows if you were correct until the effects show up. Macklem thinks about employment, GDP, housing, and the shadow of his predecessor, Mark Carney, whose influence still shapes how Canadian central bankers see their role. Ignoring all that and cutting rates because inflation dipped to 1.8% for one quarter would be a political gamble Macklem will not take.
The Safest Call Is No Call
Making a change attracts attention. Being wrong about a change guarantees you hear about it for years. Being right about a change earns you no compliments for 18 months, because monetary policy works on a lag and nobody knows if you were correct until the effects show up. The asymmetry is brutal: all the risk, none of the reward, until long after you have left the job.
Doing nothing when the data is ambiguous is the rational play. It keeps you out of the headlines. It avoids the need to explain why you moved when everyone else was holding. It gives you the option to move later if the data actually turns. Macklem has learned this lesson, and he is applying it.
Variable-rate holders benefit from the stability for now. The longer the rate holds at 2.25%, the safer their position feels. But stability is not safety. When inflation does spike, and the commodity cycle, food prices, and global bond yields all suggest it will, fixed rates will have already climbed, and the window to lock in will have closed. By the time Macklem moves, it will be too late to escape cheaply.
The last two meetings of 2026 are in October and December. Barring catastrophic data, unemployment jumping to 12%, inflation spiking to 6%, GDP collapsing by 3% in a quarter, neither will produce a change. The governor has no compelling reason to act, and in central banking, no compelling reason means no action. That is the reality for the rest of the year.
Read Next
7 Essential Checks Before You Buy in 2026: Building Confidence Through the Numbers
Getting Lenders to Count 80% of Your Gross Rent: A Checklist
820 Low-Rise Homes, 129 Condos: The GTA Slump Belongs to Speculators
200 Basis Points or 2 Percentage Points: Same Stress Test, Clearer Wording