Private Mortgage Strategy When Credit Is Damaged but Cash Flow Proves Strong: Documentation, Exit Routes and Fix-First Priorities
A Vaughan contractor depositing $18,000 a month into a business account pays $4,200 rent without missing a beat. TransUnion shows a 490 score from identity theft and a partner's discharged Consumer Proposal. No A-lender will touch the file. The private market will, but only if you structure it correctly from day one.
Private mortgages in Ontario aren't rescue loans, they're 12-month bridges with expensive tolls. In the GTA, where property values hold even when credit doesn't, lenders bet on equity and exit. FSRA's 2025-26 Supervision Plan now expects every private file to include a documented exit strategy back to traditional lending. If you can't document how the borrower refinances out in 18 months, you shouldn't be closing the deal.
What the lender actually underwrites
Private lenders ignore your beacon score. They care about three numbers: equity position, gross business deposits, and the exit math.
Equity starts at 20% in Vaughan, sometimes 25% if the credit damage is fresh. A $900,000 property needs $180,000 down minimum. The LTV ceiling is 75-80% because lenders need room to sell fast if the exit fails.
For income, forget your Notice of Assessment. A self-employed file with $60,000 net on Line 15000 probably shows $140,000 gross before write-offs. Private lenders work backwards from bank statements. Twelve months of business deposits, averaged, with large one-time items stripped out. If the contractor above shows $216,000 in annual deposits, the lender uses that figure. No tax return required, no two-year seasoning, no CMHC averaging rules. Cash in, cash counted.
The exit math runs the stress test in reverse. At 9.5% private for 12 months on a $720,000 mortgage, the monthly payment is roughly $6,100. Can this borrower pay that and still save? If yes, can they qualify at a B-lender in 2027 once the Consumer Proposal hits two years discharged and the fraud alerts clear? If the answer to either question is no, the file doesn't close.
Documentation that holds up under MBLAA
Business Bank Statements form the foundation. Twelve consecutive months, printed on bank letterhead or pulled as certified PDFs. Lenders flag deposits over $10,000 that look like transfers or refunds, those get excluded. Recurring client payments, credit card batch settlements, and e-transfer patterns all count.
For identity theft, you need a police report, a completed Equifax fraud affidavit, and a signed Consumer Statement on file with both bureaus. The statement flags the inquiries as disputed. Private lenders read those notes. A file showing six unauthorized auto loan applications in one week tells a different story than six missed payments spread across two years.
If a spouse or partner carries a Consumer Proposal, get the discharge certificate and the trustee's final statement. Ontario lenders treat an active proposal as disqualifying even when the applicant isn't named. A discharged proposal older than six months can work if the rest of the file is clean.
The 12-month priority list
Month 1-3: file fraud reports, add Consumer Statements, open a no-fee secured credit card with a $500 limit. Pay the full balance twice a month. You're repairing the score through dispute resolution and on-time secured payments.
Month 4-9: pay down any collections under $2,000. Anything larger gets negotiated but not paid until month 10, because paid collections stay on file for six years and fresh payments reset the clock on some bureau algorithms.
Month 9-12: approach a B-lender for pre-qualification. If the Consumer Proposal is discharged for 18+ months and the score has crossed 580, some B-lenders will write the deal at 6.2-7.4%. That's your exit.
Private rates in 2026 sit between 8% and 15% depending on LTV and location. Lender fees run 1-3% of the advance, paid at closing. On a $720,000 mortgage at 10.5%, the annual interest cost is $75,600. A comparable A-lender file at 5.8% costs $41,760. The gap is $33,840, that's the price of the bridge.
The rental comparison matters here. A client paying $50,400 annually in rent has already stress-tested the payment at private rates. Reframe that spend as mortgage cost and the 12-month window makes sense. But only if the exit is real.


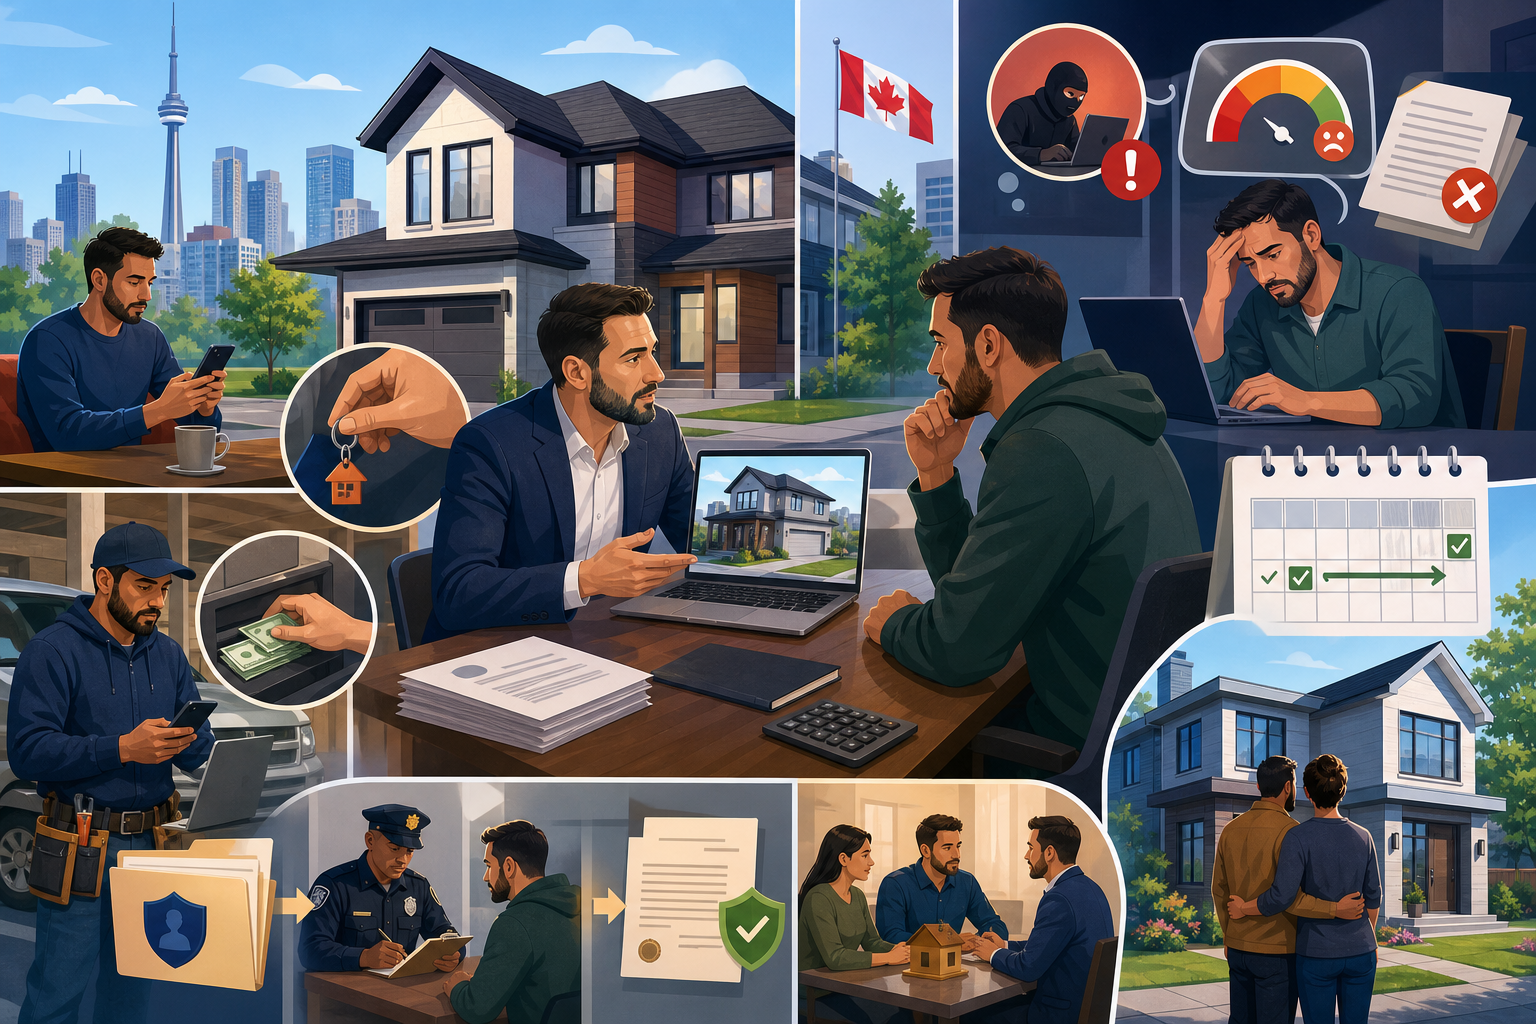

A Vaughan contractor depositing $18,000 a month into a business account pays $4,200 rent without missing a beat. TransUnion shows a 490 score from identity theft and a partner's discharged Consumer Proposal. No A-lender will touch the file. The private market will, but only if you structure it correctly from day one.
Private mortgages in Ontario aren't rescue loans, they're 12-month bridges with expensive tolls. In the GTA, where property values hold even when credit doesn't, lenders bet on equity and exit. FSRA's 2025-26 Supervision Plan now expects every private file to include a documented exit strategy back to traditional lending. If you can't document how the borrower refinances out in 18 months, you shouldn't be closing the deal.
What the lender actually underwrites
Private lenders ignore your beacon score. They care about three numbers: equity position, gross business deposits, and the exit math.
Equity starts at 20% in Vaughan, sometimes 25% if the credit damage is fresh. A $900,000 property needs $180,000 down minimum. The LTV ceiling is 75-80% because lenders need room to sell fast if the exit fails.
For income, forget your Notice of Assessment. A self-employed file with $60,000 net on Line 15000 probably shows $140,000 gross before write-offs. Private lenders work backwards from bank statements. Twelve months of business deposits, averaged, with large one-time items stripped out. If the contractor above shows $216,000 in annual deposits, the lender uses that figure. No tax return required, no two-year seasoning, no CMHC averaging rules. Cash in, cash counted.
The exit math runs the stress test in reverse. At 9.5% private for 12 months on a $720,000 mortgage, the monthly payment is roughly $6,100. Can this borrower pay that and still save? If yes, can they qualify at a B-lender in 2027 once the Consumer Proposal hits two years discharged and the fraud alerts clear? If the answer to either question is no, the file doesn't close.
Documentation that holds up under MBLAA
Business Bank Statements form the foundation. Twelve consecutive months, printed on bank letterhead or pulled as certified PDFs. Lenders flag deposits over $10,000 that look like transfers or refunds, those get excluded. Recurring client payments, credit card batch settlements, and e-transfer patterns all count.
For identity theft, you need a police report, a completed Equifax fraud affidavit, and a signed Consumer Statement on file with both bureaus. The statement flags the inquiries as disputed. Private lenders read those notes. A file showing six unauthorized auto loan applications in one week tells a different story than six missed payments spread across two years.
If a spouse or partner carries a Consumer Proposal, get the discharge certificate and the trustee's final statement. Ontario lenders treat an active proposal as disqualifying even when the applicant isn't named. A discharged proposal older than six months can work if the rest of the file is clean.
The 12-month priority list
Month 1-3: file fraud reports, add Consumer Statements, open a no-fee secured credit card with a $500 limit. Pay the full balance twice a month. You're repairing the score through dispute resolution and on-time secured payments.
Month 4-9: pay down any collections under $2,000. Anything larger gets negotiated but not paid until month 10, because paid collections stay on file for six years and fresh payments reset the clock on some bureau algorithms.
Month 9-12: approach a B-lender for pre-qualification. If the Consumer Proposal is discharged for 18+ months and the score has crossed 580, some B-lenders will write the deal at 6.2-7.4%. That's your exit.
Private rates in 2026 sit between 8% and 15% depending on LTV and location. Lender fees run 1-3% of the advance, paid at closing. On a $720,000 mortgage at 10.5%, the annual interest cost is $75,600. A comparable A-lender file at 5.8% costs $41,760. The gap is $33,840, that's the price of the bridge.
The rental comparison matters here. A client paying $50,400 annually in rent has already stress-tested the payment at private rates. Reframe that spend as mortgage cost and the 12-month window makes sense. But only if the exit is real.
Sources
Read Next
7 Essential Checks Before You Buy in 2026: Building Confidence Through the Numbers
Getting Lenders to Count 80% of Your Gross Rent: A Checklist
820 Low-Rise Homes, 129 Condos: The GTA Slump Belongs to Speculators
200 Basis Points or 2 Percentage Points: Same Stress Test, Clearer Wording