Paying Off Your Mortgage With a Windfall Locks You Into the Worst Asset You Own
A 58-year-old contractor in Mississauga receives $140,000 from the sale of a rental property and immediately directs it toward the mortgage on his principal residence. Balance drops from $380,000 to $240,000. Interest savings over the remaining amortization: roughly $68,000. The move feels disciplined, clean, final.
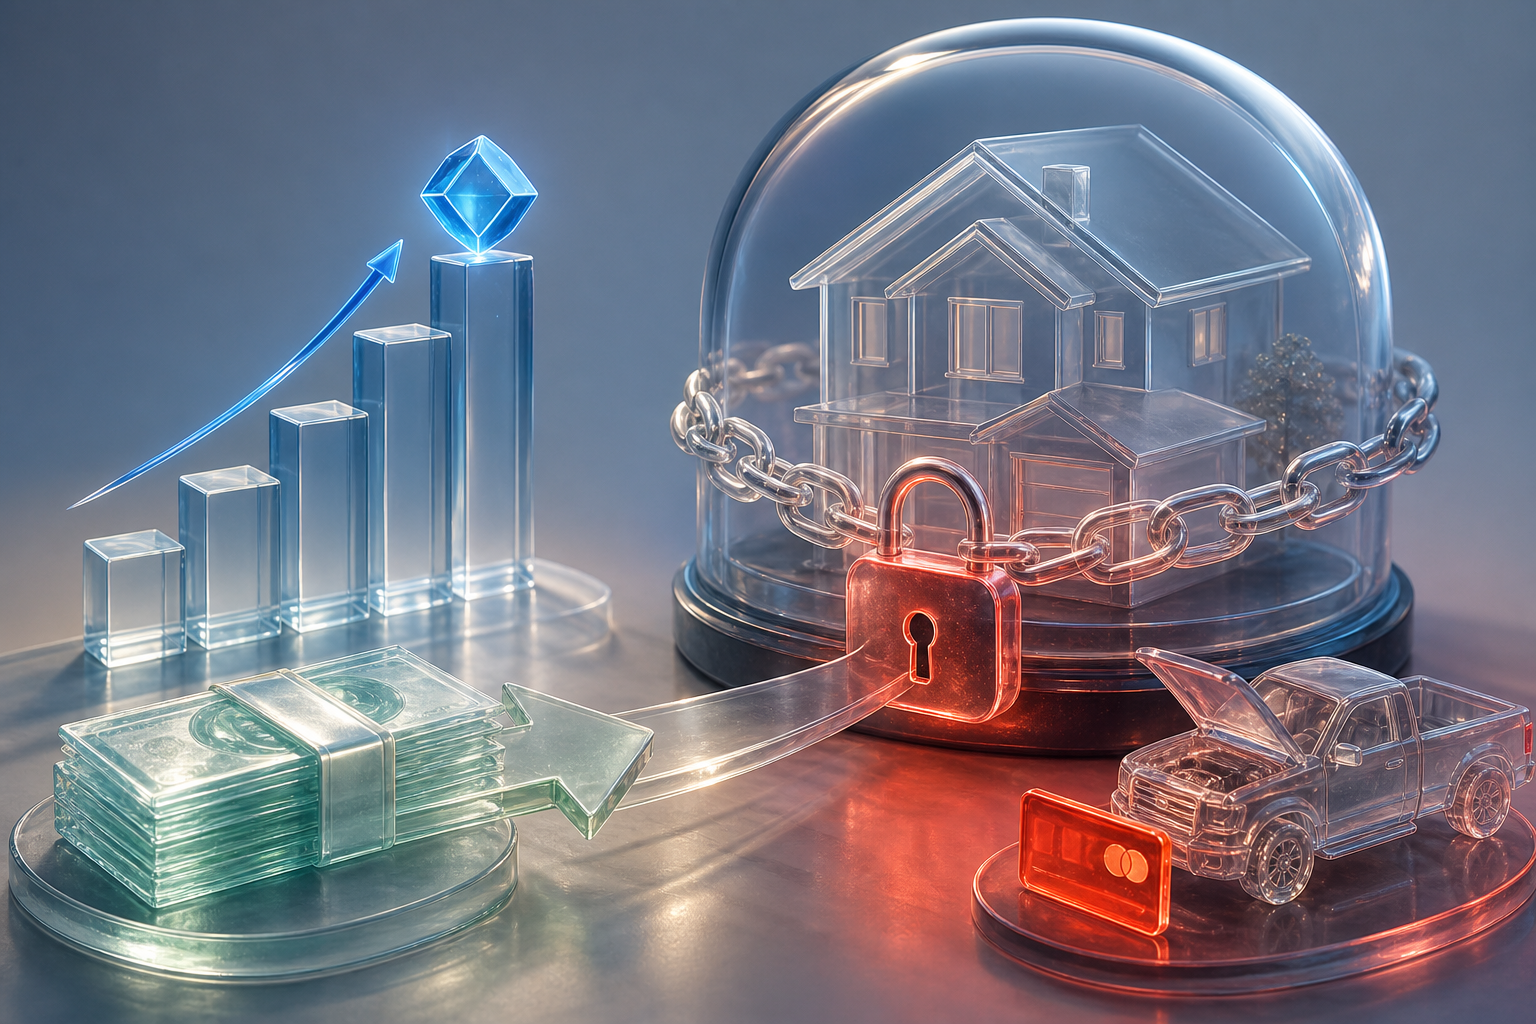
What he didn't calculate: the $140,000, invested in a balanced portfolio returning 6% annually after fees, would have grown to $187,000 in five years and $251,000 in ten. He traded that for $68,000 in avoided interest and a house he still can't spend. The emotional win cost him $119,000 in decade-long compound growth, and when his truck dies eighteen months later, he has no liquid reserves and applies for a secured line of credit at a materially higher rate to cover the replacement and a slow contract season.
You're trading growth for a balance-sheet entry you can't access
Mortgage payoff eliminates a liability. It does not create liquidity. The equity sits in the property, inaccessible unless you sell or borrow against it again, and borrowing later, especially for self-employed applicants, costs more and takes longer than keeping the capital liquid in the first place.
A $200,000 lump-sum payment on a mortgage at 4.5% saves you 4.5% annually in interest. A diversified portfolio historically returning 6, 7% after fees beats that by 150 to 250 basis points per year, compounding. The gap isn't marginal. Over ten years, $200,000 at 6% becomes $358,000. The same capital applied to mortgage principal saves you roughly $90,000 in interest on a typical 20-year amortization. You gave up $268,000 in growth to avoid $90,000 in cost.
The instinct is that debt reduction is safer. It isn't safer if the cost is eliminating your liquidity buffer in a business where income is uneven and expenses are lumpy.
Self-employed income makes this worse, not better
Contractors, consultants, commissioned salespeople, and business owners face variable monthly income and irregular large expenses. A salaried employee with stable paycheques can survive on less liquidity because the next deposit is predictable. A self-employed owner cannot.
Paying down the mortgage with a windfall when you have six-figure annual income swings is choosing the least flexible option. Real estate equity doesn't cover payroll in a slow quarter. It doesn't bridge a tax instalment. It doesn't replace a vehicle or fund a market opportunity that requires same-week capital.
If the capital stays invested and accessible, it does all of that without a credit application, without lender scrutiny of two years of financial statements, without the 24-month averaging period CMHC applies to self-employed income. Liquidity is the actual insurance. The paid-off house is a trophy.
The flexibility cost doesn't show up until you need it
Lenders price self-employed credit higher and slower than salaried credit. A contractor with $400,000 in home equity and $12,000 in savings will pay more for an operating line than the same contractor with $250,000 in equity and $150,000 in a non-registered account. The second applicant has options. The first one has to borrow, and the terms reflect that.
Mortgage payoff also eliminates your lowest-cost borrowing. If you need $80,000 in three years, you'll either refinance the mortgage (breaking your term, paying a penalty, re-qualifying at current rates and rules) or open a HELOC at prime plus 0.5% to 1%. Both cost more than keeping the original mortgage and holding liquid assets. You paid off cheap debt, then borrowed expensive debt to replace the liquidity you traded away.
Run the comparison with your actual numbers
Before putting a windfall into mortgage principal, calculate three scenarios over five and ten years: full payoff, half to mortgage and half invested, and full amount invested. Use your actual mortgage rate, your realistic after-fee investment return, and your marginal tax rate if the investment income is taxable.
Then ask: will I need this capital or borrowing capacity in the next five years for business expenses, vehicle replacement, family support, or another property purchase? If the answer is yes or maybe, the mortgage payoff just became the highest-risk move on the list.
Debt elimination feels like progress. Compound growth and liquidity are progress. One of those shows up on a statement you check once a year. The other shows up the week your income drops and your transmission fails on the same Tuesday.



A 58-year-old contractor in Mississauga receives $140,000 from the sale of a rental property and immediately directs it toward the mortgage on his principal residence. Balance drops from $380,000 to $240,000. Interest savings over the remaining amortization: roughly $68,000. The move feels disciplined, clean, final.
What he didn't calculate: the $140,000, invested in a balanced portfolio returning 6% annually after fees, would have grown to $187,000 in five years and $251,000 in ten. He traded that for $68,000 in avoided interest and a house he still can't spend. The emotional win cost him $119,000 in decade-long compound growth, and when his truck dies eighteen months later, he has no liquid reserves and applies for a secured line of credit at a materially higher rate to cover the replacement and a slow contract season.
You're trading growth for a balance-sheet entry you can't access
Mortgage payoff eliminates a liability. It does not create liquidity. The equity sits in the property, inaccessible unless you sell or borrow against it again, and borrowing later, especially for self-employed applicants, costs more and takes longer than keeping the capital liquid in the first place.
A $200,000 lump-sum payment on a mortgage at 4.5% saves you 4.5% annually in interest. A diversified portfolio historically returning 6, 7% after fees beats that by 150 to 250 basis points per year, compounding. The gap isn't marginal. Over ten years, $200,000 at 6% becomes $358,000. The same capital applied to mortgage principal saves you roughly $90,000 in interest on a typical 20-year amortization. You gave up $268,000 in growth to avoid $90,000 in cost.
The instinct is that debt reduction is safer. It isn't safer if the cost is eliminating your liquidity buffer in a business where income is uneven and expenses are lumpy.
Self-employed income makes this worse, not better
Contractors, consultants, commissioned salespeople, and business owners face variable monthly income and irregular large expenses. A salaried employee with stable paycheques can survive on less liquidity because the next deposit is predictable. A self-employed owner cannot.
Paying down the mortgage with a windfall when you have six-figure annual income swings is choosing the least flexible option. Real estate equity doesn't cover payroll in a slow quarter. It doesn't bridge a tax instalment. It doesn't replace a vehicle or fund a market opportunity that requires same-week capital.
If the capital stays invested and accessible, it does all of that without a credit application, without lender scrutiny of two years of financial statements, without the 24-month averaging period CMHC applies to self-employed income. Liquidity is the actual insurance. The paid-off house is a trophy.
The flexibility cost doesn't show up until you need it
Lenders price self-employed credit higher and slower than salaried credit. A contractor with $400,000 in home equity and $12,000 in savings will pay more for an operating line than the same contractor with $250,000 in equity and $150,000 in a non-registered account. The second applicant has options. The first one has to borrow, and the terms reflect that.
Mortgage payoff also eliminates your lowest-cost borrowing. If you need $80,000 in three years, you'll either refinance the mortgage (breaking your term, paying a penalty, re-qualifying at current rates and rules) or open a HELOC at prime plus 0.5% to 1%. Both cost more than keeping the original mortgage and holding liquid assets. You paid off cheap debt, then borrowed expensive debt to replace the liquidity you traded away.
Run the comparison with your actual numbers
Before putting a windfall into mortgage principal, calculate three scenarios over five and ten years: full payoff, half to mortgage and half invested, and full amount invested. Use your actual mortgage rate, your realistic after-fee investment return, and your marginal tax rate if the investment income is taxable.
Then ask: will I need this capital or borrowing capacity in the next five years for business expenses, vehicle replacement, family support, or another property purchase? If the answer is yes or maybe, the mortgage payoff just became the highest-risk move on the list.
Debt elimination feels like progress. Compound growth and liquidity are progress. One of those shows up on a statement you check once a year. The other shows up the week your income drops and your transmission fails on the same Tuesday.
Sources
Read Next
7 Essential Checks Before You Buy in 2026: Building Confidence Through the Numbers
Getting Lenders to Count 80% of Your Gross Rent: A Checklist
820 Low-Rise Homes, 129 Condos: The GTA Slump Belongs to Speculators
200 Basis Points or 2 Percentage Points: Same Stress Test, Clearer Wording