One Word Changes CMHC's Self-Employed Rule: 24 Months Must Be Consecutive
A self-employed buyer can hold two full years of financial statements and still be told they don't qualify for an insured mortgage. The reason sits in one word. CMHC's self-employed guidance, as it reads in fall 2026, asks for 24 consecutive months of financial statements for high-ratio mortgages.
That word matters to anyone buying with less than 20% down, since mortgage insurance kicks in above 80% loan-to-value. A stretch where the business went quiet, a contract role on someone else's payroll, a gap between one venture and the next: any of these can reset the count. If you're planning a purchase in Vaughan or anywhere in Ontario, or you advise clients who are, the work is protecting an unbroken run of income, and that work starts well before anyone books a showing.
Count your months backward from today. Most people count tax years filed. Lenders follow the calendar. Start at this month and walk back, checking that every month has business activity behind it. People skip this because "two years" feels like it's already done.
Mark every gap, however short. A season you stopped invoicing, a few months of employment between ventures, a business you wound down and restarted. Write them down with dates. Whether a lender treats a given gap as a break is a conversation to have early, because finding it at underwriting leaves no time to fix anything.
Hold off on restructuring before you buy. Incorporating, changing business names or folding one company into another can make a continuous record harder to follow on paper. A lender has to see one line of income running through 24 months. Talk to your mortgage agent before the paperwork with your accountant, since the order of those two calls changes the outcome.
Check whether insurance applies to you at all. At 20% down or more, you sit at or under the 80% threshold and the insured rules don't apply in the same way. Below that, CMHC's self-employed program also caps the purchase price at $1.5M for homeowner loans and $1.0M for small rental loans, which rules out a fair share of detached homes in York Region. The premium is real money too: at 10% down, it's 3.10% of the mortgage amount.
Map the clock before deciding what to do with a windfall. An inheritance, a business sale or a big bonus tempts people to pay down debt or reinvest in the company. If your consecutive months come up short, that same money might be what gets you to 20% down and out of the insured rules altogether. Once it's spent elsewhere, that option is gone.
Ask whether the gross-up applies to your file. CMHC allows a 15% gross-up on self-employed income in some cases, which helps owners whose reported income is lean after legitimate write-offs. It won't rescue a broken timeline, but on a clean 24-month record it can be the difference on your debt ratios.
Put the month count in the file a year ahead. If you plan for self-employed clients, add a running tally of consecutive months to their annual review. A client who wants to buy next spring needs to know this fall whether a gap from two years ago is about to roll out of the window or land right in the middle of it.
The fix for a broken run is usually time, and time is the one thing nobody can produce at the last minute. Count your months this week, before a purchase date starts counting for you.


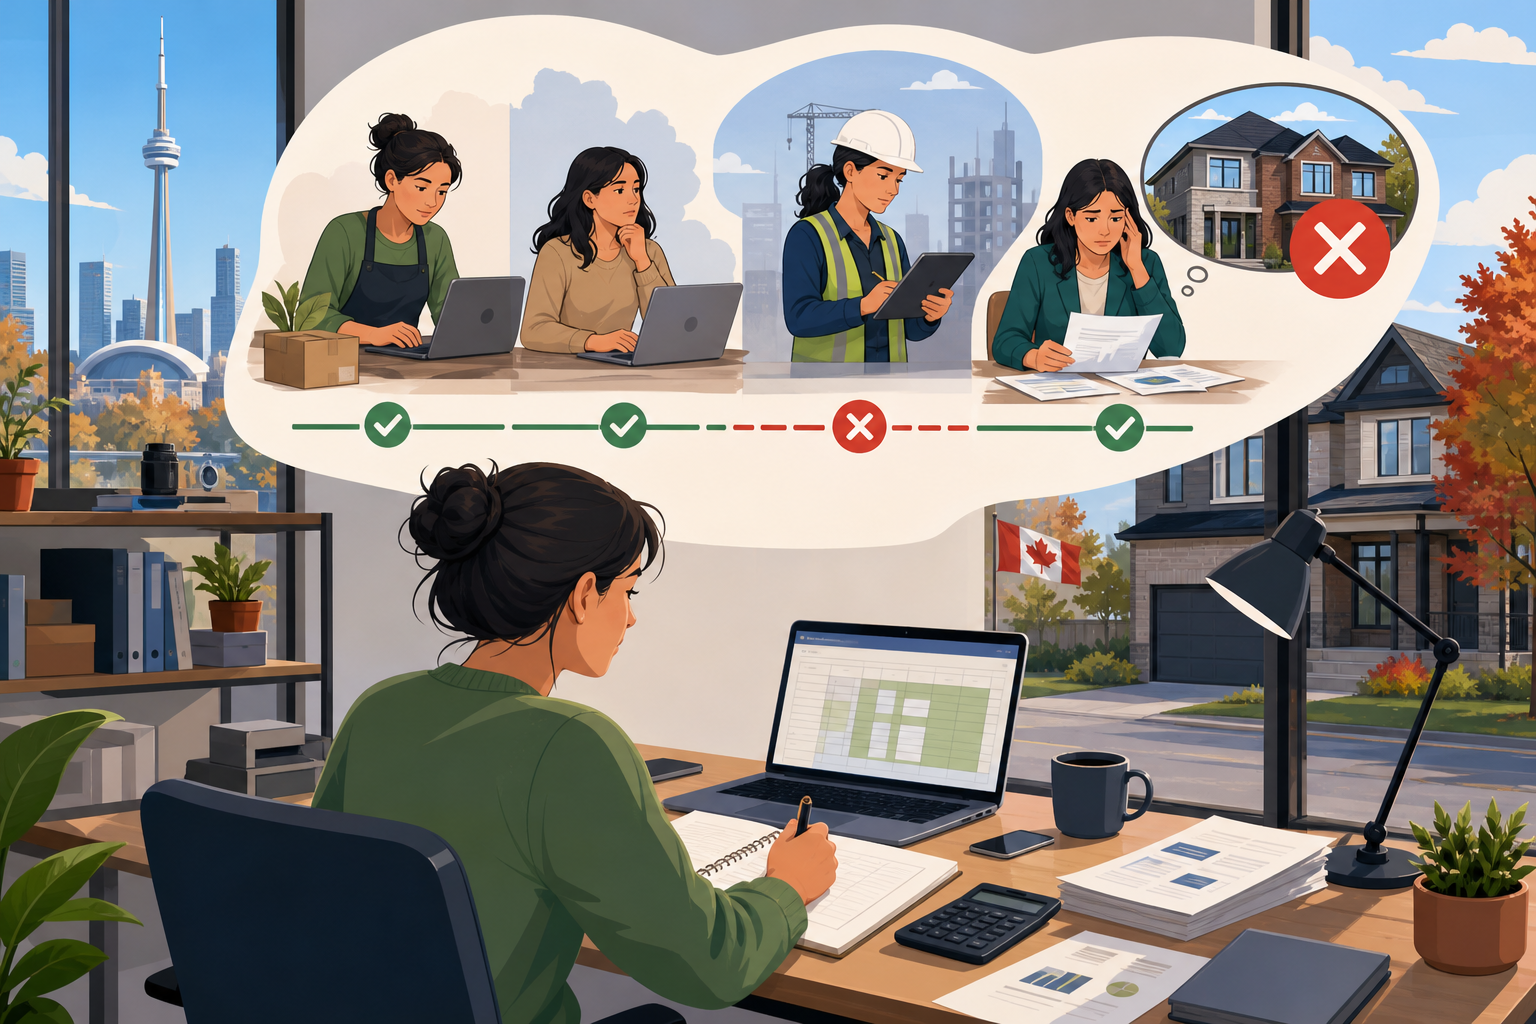

A self-employed buyer can hold two full years of financial statements and still be told they don't qualify for an insured mortgage. The reason sits in one word. CMHC's self-employed guidance, as it reads in fall 2026, asks for 24 consecutive months of financial statements for high-ratio mortgages.
That word matters to anyone buying with less than 20% down, since mortgage insurance kicks in above 80% loan-to-value. A stretch where the business went quiet, a contract role on someone else's payroll, a gap between one venture and the next: any of these can reset the count. If you're planning a purchase in Vaughan or anywhere in Ontario, or you advise clients who are, the work is protecting an unbroken run of income, and that work starts well before anyone books a showing.
The fix for a broken run is usually time, and time is the one thing nobody can produce at the last minute. Count your months this week, before a purchase date starts counting for you.
Read Next
7 Essential Checks Before You Buy in 2026: Building Confidence Through the Numbers
Getting Lenders to Count 80% of Your Gross Rent: A Checklist
820 Low-Rise Homes, 129 Condos: The GTA Slump Belongs to Speculators
200 Basis Points or 2 Percentage Points: Same Stress Test, Clearer Wording