Couche-Tard Beats Q1 Estimates While Lululemon Cuts 2026 Outlook: What Changed
Alimentation Couche-Tard reported Q1 2026 net income of roughly $830 million USD, up from $782.5 million in the same quarter a year earlier. Lululemon Athletica, over the same period, revised its full-year revenue forecast to show a decline of 5-7%, abandoning the growth projections it had been carrying. Both companies reported within days of each other. The market sent Couche-Tard up 8% and knocked Lululemon down 17%. The divergence isn't about one company executing well and the other stumbling. It's about which side of the consumer spending ledger you're standing on in September 2026.
The Convenience Play Is Fuel Plus Food
Couche-Tard's Q1 beat came from two places: fuel margins held up better than expected, and the European assets it acquired from TotalEnergies are now fully integrated and contributing to the top line. The company operates over 16,700 stores globally as of mid-2026. What matters more than the store count is what happens inside the store. Fuel gets people through the door. The margin is on the sandwich, the coffee, the energy drink they pick up on the way out.
This is the part of retail that works when consumers are cautious. A $4.50 iced coffee is a habit spend. It doesn't require a good quarter or a bonus clearing. It just requires a Tuesday. Couche-Tard has spent the last three years turning its footprint into a food-service network. Customers now buy sandwiches, coffee, and energy drinks on their way out, and those margins are what's keeping same-store sales positive even as overall retail discretionary spend softens across North America.
The other tailwind: cheaper debt. The Bank of Canada has been in a lowering cycle since early 2026, and Couche-Tard is a serial acquirer. Lower rates improve the company's ability to finance future acquisitions. Couche-Tard previously pursued Seven & i Holdings (the parent company of 7-Eleven) with bids reaching $47 billion, but withdrew its proposal in mid-2025 after extended negotiations failed to produce an agreement.
The Premium Apparel Problem Is Newness
Lululemon's Q2 earnings showed the company is still profitable, operating margins remain above 20%, which is exceptional for apparel retail. The issue is growth. Comparable store sales in the U.S. and Canada declined 9%. The women's line, which is still two-thirds of revenue, hasn't had a breakout product in over a year. The ABC pant and the Align legging are mature SKUs. When your core product is mature and your customer base is saturated, you need innovation to keep comparable sales moving. Lululemon hasn't delivered that in North America.
China has weakened, with revenue declining 2% in constant currency during the latest quarter. But China is 15% of revenue. The company is clearing seasonal items at a discount to make room for a technical outerwear line that won't hit stores until late Q4, which is a real drag on near-term margins. That's a bet that the next wave of product is strong enough to reignite momentum. The market isn't pricing that bet as likely.
Where the Thesis Flips
The Couche-Tard story depends on internal combustion engines staying dominant for another decade. If EV adoption accelerates faster than the current trajectory, say, 40% of new car sales by 2030 instead of the projected 25%, the fuel margin collapses and the real estate model breaks. The food-service pivot buys time, but it doesn't replace fuel as the anchor.
Lululemon's thesis flips if the next product cycle lands. A viral legging, a men's line that actually converts, a footwear launch that doesn't get buried, any of those could bring comparable sales back into positive territory and the stock would re-rate quickly. Premium apparel is only ever one hit away from a growth resurgence.
Right now, Couche-Tard is benefiting from the consumer trading down into frequency. Lululemon is suffering from the consumer trading out of premium discretionary. Both are temporary positions. Neither is the end state.


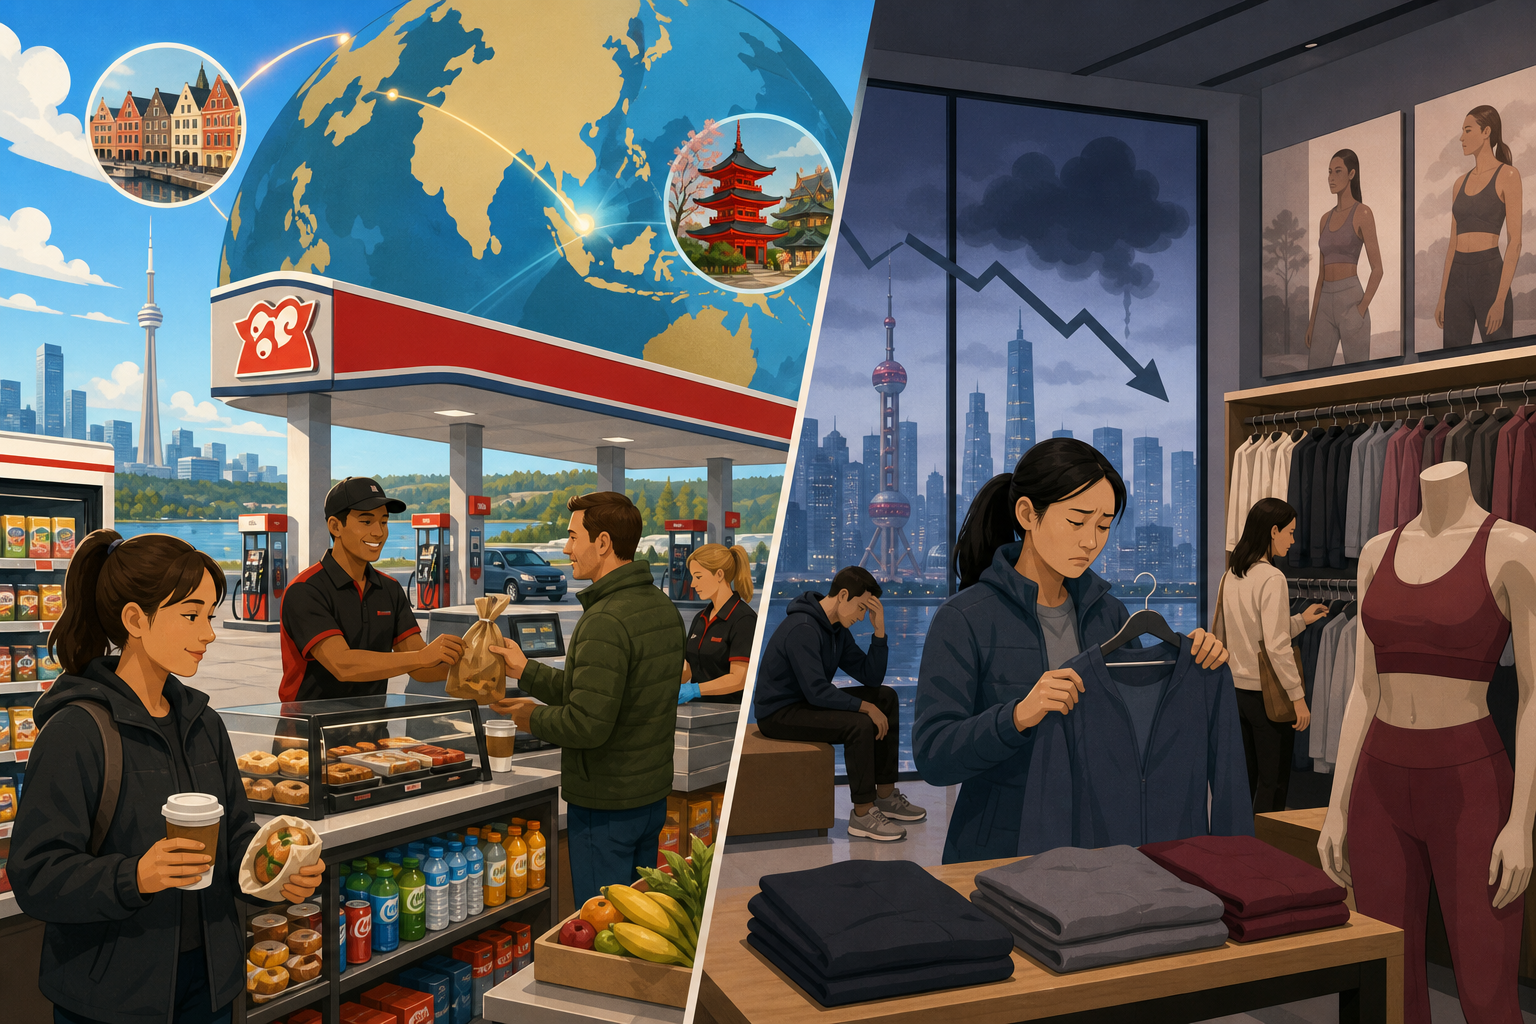

Alimentation Couche-Tard reported Q1 2026 net income of roughly $830 million USD, up from $782.5 million in the same quarter a year earlier. Lululemon Athletica, over the same period, revised its full-year revenue forecast to show a decline of 5-7%, abandoning the growth projections it had been carrying. Both companies reported within days of each other. The market sent Couche-Tard up 8% and knocked Lululemon down 17%. The divergence isn't about one company executing well and the other stumbling. It's about which side of the consumer spending ledger you're standing on in September 2026.
The Convenience Play Is Fuel Plus Food
Couche-Tard's Q1 beat came from two places: fuel margins held up better than expected, and the European assets it acquired from TotalEnergies are now fully integrated and contributing to the top line. The company operates over 16,700 stores globally as of mid-2026. What matters more than the store count is what happens inside the store. Fuel gets people through the door. The margin is on the sandwich, the coffee, the energy drink they pick up on the way out.
This is the part of retail that works when consumers are cautious. A $4.50 iced coffee is a habit spend. It doesn't require a good quarter or a bonus clearing. It just requires a Tuesday. Couche-Tard has spent the last three years turning its footprint into a food-service network. Customers now buy sandwiches, coffee, and energy drinks on their way out, and those margins are what's keeping same-store sales positive even as overall retail discretionary spend softens across North America.
The other tailwind: cheaper debt. The Bank of Canada has been in a lowering cycle since early 2026, and Couche-Tard is a serial acquirer. Lower rates improve the company's ability to finance future acquisitions. Couche-Tard previously pursued Seven & i Holdings (the parent company of 7-Eleven) with bids reaching $47 billion, but withdrew its proposal in mid-2025 after extended negotiations failed to produce an agreement.
The Premium Apparel Problem Is Newness
Lululemon's Q2 earnings showed the company is still profitable, operating margins remain above 20%, which is exceptional for apparel retail. The issue is growth. Comparable store sales in the U.S. and Canada declined 9%. The women's line, which is still two-thirds of revenue, hasn't had a breakout product in over a year. The ABC pant and the Align legging are mature SKUs. When your core product is mature and your customer base is saturated, you need innovation to keep comparable sales moving. Lululemon hasn't delivered that in North America.
China has weakened, with revenue declining 2% in constant currency during the latest quarter. But China is 15% of revenue. The company is clearing seasonal items at a discount to make room for a technical outerwear line that won't hit stores until late Q4, which is a real drag on near-term margins. That's a bet that the next wave of product is strong enough to reignite momentum. The market isn't pricing that bet as likely.
Where the Thesis Flips
The Couche-Tard story depends on internal combustion engines staying dominant for another decade. If EV adoption accelerates faster than the current trajectory, say, 40% of new car sales by 2030 instead of the projected 25%, the fuel margin collapses and the real estate model breaks. The food-service pivot buys time, but it doesn't replace fuel as the anchor.
Lululemon's thesis flips if the next product cycle lands. A viral legging, a men's line that actually converts, a footwear launch that doesn't get buried, any of those could bring comparable sales back into positive territory and the stock would re-rate quickly. Premium apparel is only ever one hit away from a growth resurgence.
Right now, Couche-Tard is benefiting from the consumer trading down into frequency. Lululemon is suffering from the consumer trading out of premium discretionary. Both are temporary positions. Neither is the end state.
Sources
Read Next
7 Essential Checks Before You Buy in 2026: Building Confidence Through the Numbers
Getting Lenders to Count 80% of Your Gross Rent: A Checklist
820 Low-Rise Homes, 129 Condos: The GTA Slump Belongs to Speculators
200 Basis Points or 2 Percentage Points: Same Stress Test, Clearer Wording