CMHC's 24-Month Rule: How a Gap in Your Statements Moves Your Closing Date
Consider a self-employed electrician in Vaughan, a sole proprietor with a steady book of renovation clients and two filed Notices of Assessment showing income that held up from one year to the next. In the spring of 2026 they found a townhouse priced comfortably below CMHC's $1.5M ceiling for insured purchases, had a little over 10% saved for the down payment, and signed an offer with the standard five-day financing condition. On paper, the file looked ordinary.
What the file did not show at a glance was a stretch in late 2024 when the business went quiet. A parent was ill. For roughly three months there were no invoices, no business deposits, and no bookkeeping, because there was nothing to book. The electrician came back to work, the year finished strong, and the tax return was filed on time. It felt like a pause, not a break. Most people would have read it the same way.
Where the timeline turned
High-ratio mortgages, the ones with less than 20% down where default insurance is mandatory, run on CMHC's self-employed rules. CMHC's self-employed fact sheet recommends at least 24 months operating the business, and lenders read that as 24 consecutive months of records. Not any 24 months. Not the strongest 24 months pieced together around a gap.
The lender's underwriter flagged it on day three. The business had operated for more than two years in total, but not for two years without interruption. The income averaging lenders apply to self-employed borrowers, using line 15000 income that CMHC allows to be grossed up by 15% to account for business expenses, depends on that continuous record. With a hole in it, the averaging had nothing stable to stand on.
That was the turn. The question stopped being how much the electrician earned and became when the record would be whole again.
The cost of the gap
A three-month pause does not cost three months. Counted from the point where activity resumed, a consecutive 24-month history would not exist until late 2026, and the lender would still want the NOA that confirms it. In a file like this, that pushes a realistic insured approval into 2027.
The options on day four were narrow. The seller would not extend the condition indefinitely. An alternative lender that leans on bank statements rather than NOAs was possible in principle, but those programs typically require 20% down and carry higher rates, and the electrician had 10%. CMHC does sometimes allow a shorter history when the borrower worked in the same field as a salaried employee right before going out on their own, but that exception describes someone who changed how they were paid, not someone who stopped working for a season.
The condition was not waived. The deal fell away.
What the file needed earlier
None of this required a different business. It required a different calendar. For a self-employed buyer, that looks like:
Map the last 24 months against your bank deposits and bookkeeping before you look at listings, and write down any month with no business activity.
Confirm both NOAs are filed and that nothing is owing to CRA, since an unpaid balance can leave the history treated as incomplete.
If a gap exists, have a mortgage agent date the point at which your consecutive record becomes whole, and plan the purchase from that date.
Remember that the stress test still applies: you qualify at the higher of your contract rate plus 2% or 5.25%, so the averaged income has to carry a payment above what you will actually pay.
For real estate agents in York Region, the question to ask before the first showing is whether the buyer has two full years of filed NOAs with no break in business activity between them. If the answer has any hesitation in it, a five-day financing condition is the wrong instrument. Ask for more time, or have the buyer pre-qualified against the actual documents before writing the offer.
The electrician's records will become a clean 24-month run at the end of this year. The NOA that closes the loop arrives next spring. The next offer, whenever it gets written, will start from that date rather than from the listing.


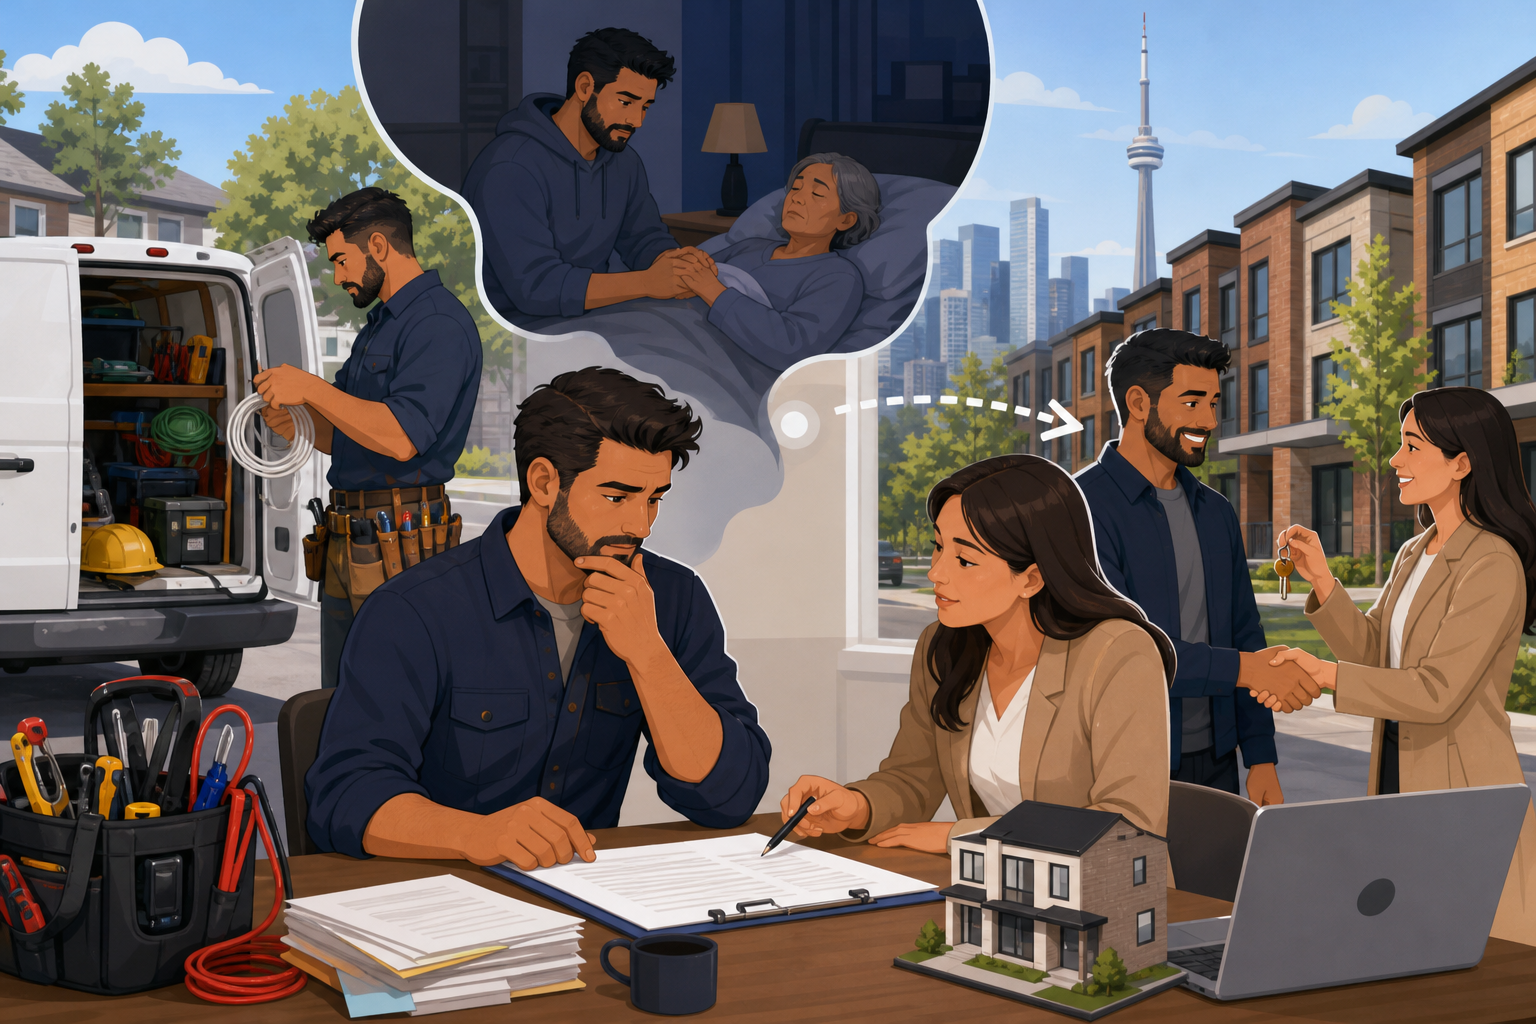

Consider a self-employed electrician in Vaughan, a sole proprietor with a steady book of renovation clients and two filed Notices of Assessment showing income that held up from one year to the next. In the spring of 2026 they found a townhouse priced comfortably below CMHC's $1.5M ceiling for insured purchases, had a little over 10% saved for the down payment, and signed an offer with the standard five-day financing condition. On paper, the file looked ordinary.
What the file did not show at a glance was a stretch in late 2024 when the business went quiet. A parent was ill. For roughly three months there were no invoices, no business deposits, and no bookkeeping, because there was nothing to book. The electrician came back to work, the year finished strong, and the tax return was filed on time. It felt like a pause, not a break. Most people would have read it the same way.
Where the timeline turned
High-ratio mortgages, the ones with less than 20% down where default insurance is mandatory, run on CMHC's self-employed rules. CMHC's self-employed fact sheet recommends at least 24 months operating the business, and lenders read that as 24 consecutive months of records. Not any 24 months. Not the strongest 24 months pieced together around a gap.
The lender's underwriter flagged it on day three. The business had operated for more than two years in total, but not for two years without interruption. The income averaging lenders apply to self-employed borrowers, using line 15000 income that CMHC allows to be grossed up by 15% to account for business expenses, depends on that continuous record. With a hole in it, the averaging had nothing stable to stand on.
That was the turn. The question stopped being how much the electrician earned and became when the record would be whole again.
The cost of the gap
A three-month pause does not cost three months. Counted from the point where activity resumed, a consecutive 24-month history would not exist until late 2026, and the lender would still want the NOA that confirms it. In a file like this, that pushes a realistic insured approval into 2027.
The options on day four were narrow. The seller would not extend the condition indefinitely. An alternative lender that leans on bank statements rather than NOAs was possible in principle, but those programs typically require 20% down and carry higher rates, and the electrician had 10%. CMHC does sometimes allow a shorter history when the borrower worked in the same field as a salaried employee right before going out on their own, but that exception describes someone who changed how they were paid, not someone who stopped working for a season.
The condition was not waived. The deal fell away.
What the file needed earlier
None of this required a different business. It required a different calendar. For a self-employed buyer, that looks like:
For real estate agents in York Region, the question to ask before the first showing is whether the buyer has two full years of filed NOAs with no break in business activity between them. If the answer has any hesitation in it, a five-day financing condition is the wrong instrument. Ask for more time, or have the buyer pre-qualified against the actual documents before writing the offer.
The electrician's records will become a clean 24-month run at the end of this year. The NOA that closes the loop arrives next spring. The next offer, whenever it gets written, will start from that date rather than from the listing.
Sources
Read Next
7 Essential Checks Before You Buy in 2026: Building Confidence Through the Numbers
Getting Lenders to Count 80% of Your Gross Rent: A Checklist
820 Low-Rise Homes, 129 Condos: The GTA Slump Belongs to Speculators
200 Basis Points or 2 Percentage Points: Same Stress Test, Clearer Wording